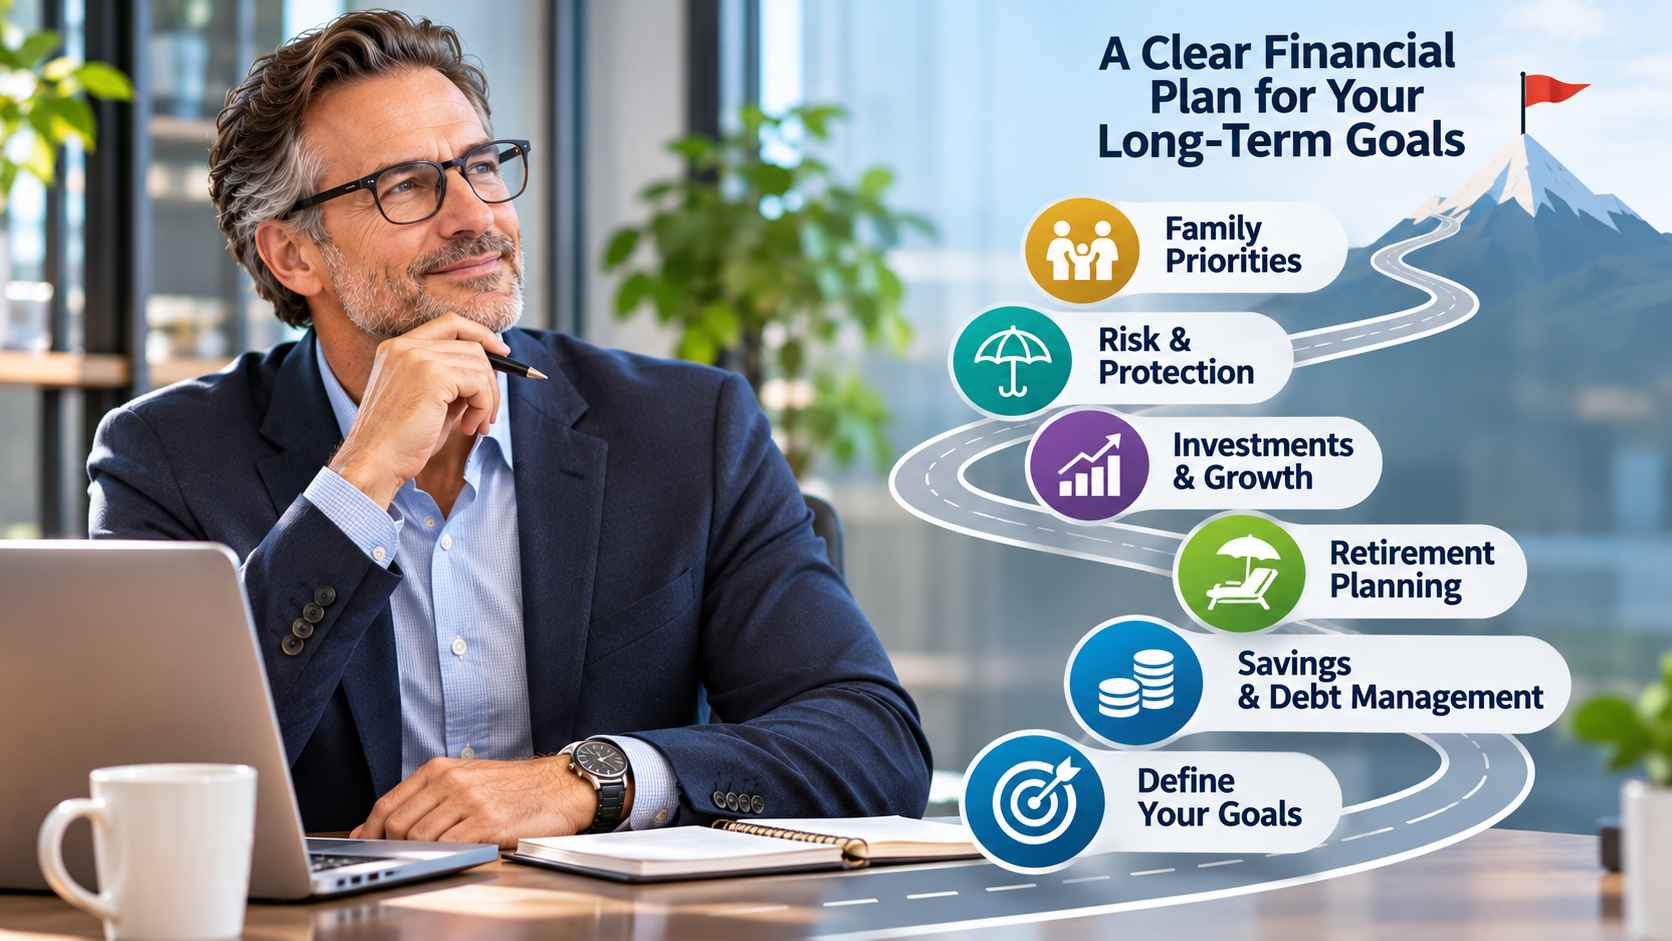
A demanding career can leave little room for managing personal finances. Between professional responsibilities, family commitments, meetings, and everyday decisions, financial planning is often postponed until something important changes.
For executives, incorporated professionals, and high-income households, this can create an unusual situation: earning a substantial income while having limited time to evaluate long-term financial goals.
A strong salary may provide financial flexibility, but it does not automatically create lasting financial security. Spending habits, debt, investment decisions, retirement needs, and unexpected circumstances all influence financial well-being.
Developing a structured financial plan can help busy professionals organize these responsibilities without allowing money management to become another overwhelming task.
Why a High Income Does Not Automatically Mean Financial Security
A high income creates opportunities, but financial security depends on more than earnings.
Professionals may have significant expenses involving mortgages, childcare, education, transportation, and lifestyle commitments.
As income increases, spending can also expand.
For example, an executive receiving a promotion may decide to purchase a larger home or take on additional financial obligations.
These decisions are not necessarily inappropriate, but they can reduce the amount available for saving and investing.
Financial security involves understanding the relationship between income, expenses, assets, liabilities, and future requirements.
Someone earning less but maintaining manageable obligations may have greater financial flexibility than a higher-income professional with substantial recurring commitments.
Setting Financial Priorities Around Personal Goals
Effective financial planning begins with understanding what money is intended to accomplish.
For some professionals, the primary goal may be preparing for retirement. Others may prioritize supporting children, purchasing property, or creating greater flexibility in their careers.
These objectives often compete for financial resources.
Identify Immediate Priorities
Short-term goals might include managing household expenses, reducing certain debts, or establishing accessible savings.
Consider Long-Term Objectives
Longer-term priorities may involve retirement, education funding, family support, or eventual estate transfers.
A useful approach is to distinguish essential commitments from optional goals.
For example, a professional planning to reduce working hours in the future may need to balance current lifestyle expenses with additional retirement savings.
Clearly defined priorities provide direction when financial decisions become complicated.
Understanding Cash Flow and Spending Patterns
Busy professionals sometimes focus on investment performance while overlooking everyday cash flow.
However, understanding how money enters and leaves a household is fundamental to financial planning.
A cash flow review considers employment income, recurring expenses, debt payments, savings, and discretionary spending.
For example, a household may have strong combined earnings but limited remaining cash after mortgage payments, education expenses, and other commitments.
Reviewing these patterns helps identify how much flexibility exists.
The objective is not necessarily to eliminate enjoyable spending.
Instead, it is to understand whether current financial habits support future goals.
Automated payments and savings arrangements may also make routine financial management easier, provided sufficient funds remain available for obligations.
Balancing Savings, Debt, and Investment Accounts
Savings, borrowing, and investing are interconnected financial decisions.
Professionals may hold mortgages, personal loans, registered investments, and other financial assets simultaneously.
Reviewing Debt Obligations
Debt should be evaluated according to borrowing costs, repayment terms, cash flow, and individual circumstances.
Repaying every obligation immediately is not automatically the most appropriate strategy.
Building Accessible Savings
Emergency reserves can provide financial flexibility when unexpected expenses or income interruptions occur.
The appropriate amount depends on household responsibilities and income stability.
Organizing Investment Accounts
Canadian professionals may use Registered Retirement Savings Plans (RRSPs), Tax-Free Savings Accounts (TFSAs), and other investment arrangements, subject to applicable rules.
These accounts serve different purposes and have distinct tax considerations.
Rather than managing each account independently, individuals can consider how their combined financial resources support broader goals.
Preparing for Retirement While Managing Present Responsibilities
Retirement planning can be difficult when professional responsibilities demand immediate attention.
However, postponing the discussion may leave less flexibility when circumstances change.
Retirement preparation involves more than selecting an intended retirement age.
Professionals should consider future living expenses, potential income sources, outstanding obligations, and desired lifestyle.
For example, someone hoping to transition into part-time consulting may have different retirement needs from an individual planning to stop working completely.
Consider Different Scenarios
Financial planning can explore how changes in retirement timing, spending, or income may affect long-term requirements.
These scenarios depend on assumptions and cannot guarantee future outcomes.
Professional personalized financial planning can help individuals connect retirement objectives with current financial responsibilities.
Understanding Investment Risk and Time Horizons
Investment decisions should reflect more than potential returns.
Financial objectives, time horizons, liquidity needs, and risk tolerance all influence the suitability of different approaches.
For example, money intended for a near-term property purchase serves a different purpose from assets invested for retirement decades away.
A professional who already holds substantial company shares may also need to consider how employment-related investments affect overall portfolio concentration.
Diversification can help manage exposure to particular assets or markets, but it does not eliminate investment risk.
Regular portfolio reviews provide opportunities to evaluate whether existing holdings remain consistent with changing financial priorities.
No investment strategy can guarantee positive returns or prevent losses.
Reviewing Plans After Major Life Changes
A financial plan should evolve alongside personal and professional circumstances.
A promotion, career transition, marriage, separation, inheritance, or change in family responsibilities may affect income and financial priorities.
For example, an incorporated professional who becomes a business owner may need to reconsider compensation arrangements, retirement planning, and financial reserves.
Similarly, a household welcoming a child may want to review education savings and insurance needs.
These events do not always require a complete financial restructuring.
However, they provide useful opportunities to revisit existing assumptions.
Scheduling periodic reviews can help ensure that financial arrangements remain relevant rather than relying on decisions made years earlier.
Connecting Financial Planning With Tax and Estate Considerations
Financial decisions can have tax and estate implications that deserve coordinated attention.
For example, compensation arrangements, investment account choices, charitable giving, and retirement withdrawals may involve different tax considerations.
Estate planning introduces additional questions involving wills, beneficiary designations, powers of attorney, and the intended distribution of assets.
These responsibilities often require collaboration between qualified financial, tax, and legal professionals.
FP Canada provides financial planning resources and professional standards covering areas such as investment planning, retirement, taxation, insurance, and estate considerations.
This broader perspective reinforces the importance of evaluating financial decisions together rather than treating each issue as unrelated.
Creating a Financial Roadmap That Fits a Busy Schedule
A financial plan does not need to involve reviewing investments every day.
For professionals with demanding schedules, a structured process may be more practical.
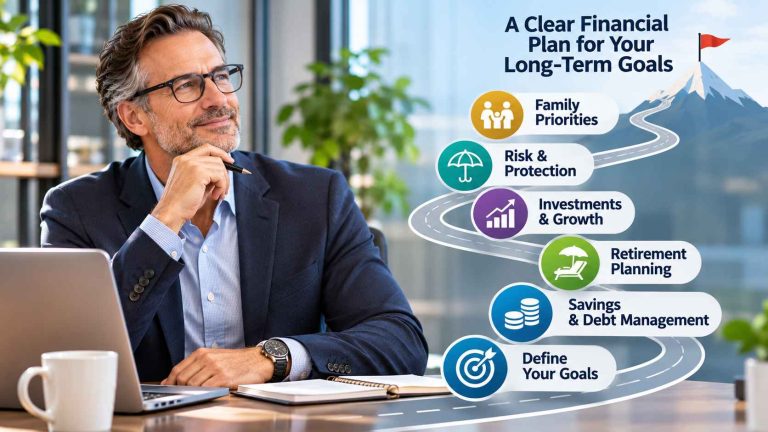
Useful steps include:
- Define financial goals: Identify immediate, medium-term, and long-term priorities.
- Review the household balance sheet: Understand existing assets and liabilities.
- Evaluate cash flow: Determine how income supports spending, saving, and debt obligations.
- Review investments: Consider portfolio allocation, risk, and time horizons.
- Assess protection needs: Review insurance and emergency resources.
- Coordinate professional advice: Address financial, tax, and estate considerations where appropriate.
- Schedule regular reviews: Update the plan when circumstances or objectives change.
This approach can provide a clearer framework without requiring constant attention to financial markets.
The Value of Working With Qualified Financial Professionals
Managing complex financial responsibilities alongside a demanding career can require considerable time and specialized knowledge.
Financial planners and investment professionals may help individuals organize information, evaluate different scenarios, and coordinate decisions.
For example, an executive approaching retirement may need to consider investments, pension arrangements, taxes, and family priorities together.
Exponent Investment Management provides financial planning and investment management services for Canadian professionals and households.
When selecting professional assistance, individuals should review qualifications, relevant experience, fees, services offered, and potential conflicts of interest.
Professional guidance can support informed decision-making, but it cannot guarantee financial independence or investment performance.
Making Long-Term Financial Planning a Sustainable Priority
Busy professionals do not need to manage every financial detail personally or make major decisions continuously.
A practical financial roadmap can help organize savings, debt, investments, retirement expectations, and family responsibilities around clearly defined priorities.
The value of planning lies in understanding the complete financial picture and reviewing it as circumstances evolve.
A high income may create opportunities, but thoughtful decisions about spending, saving, risk, and future obligations remain important.
By making time for structured financial reviews and seeking qualified guidance when appropriate, professionals can approach long-term financial decisions with greater clarity while continuing to focus on their careers and personal lives.